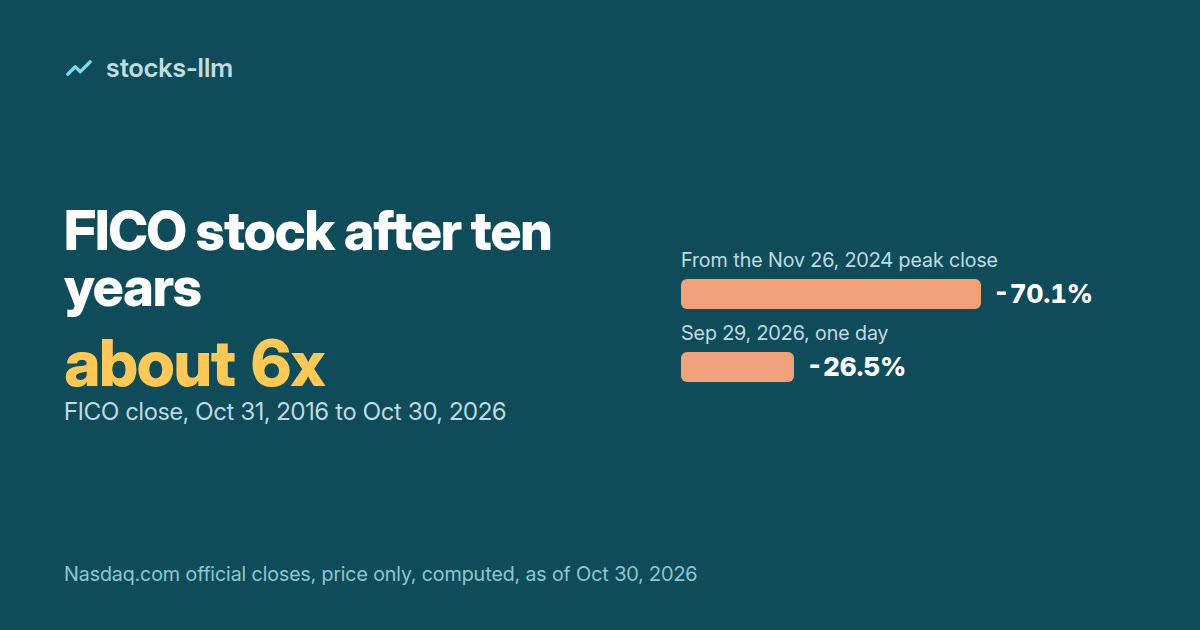
FICO stock after ten years: about 6x higher, 70% below its peak
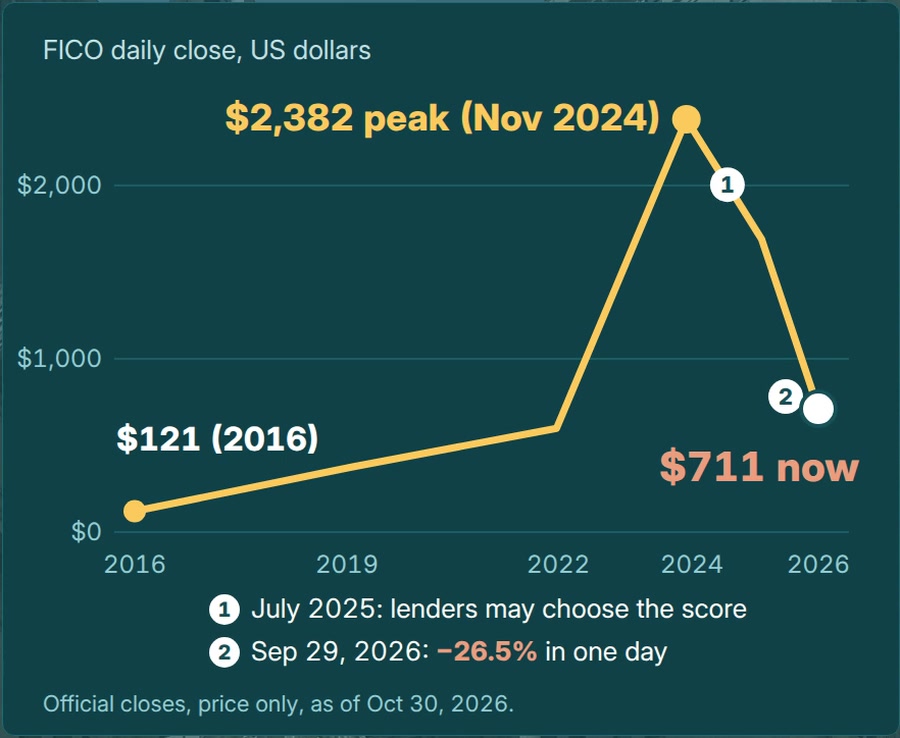
FICO stock closed at $711.23 on October 30, 2026, about 6 times its close of $120.68 ten years earlier, but about 70% below its highest close of $2,382.40 on November 26, 2024. Both comparisons are computed from official daily closes, price only, not total return.
FICO, formally Fair Isaac, makes the credit score model that lenders read when someone applies for a mortgage, a card or a car loan. The company says its score is used in most US credit decisions and by 90% of top US lenders. FICO does not compute most scores itself: the credit bureaus run its model on their own files. Most FICO scores are sold through those bureaus, which pay FICO a fee for each one, and the company also sells some scores directly.
The clearest view of that fee is the mortgage score. FICO's chief executive wrote in March 2024 that mortgage lenders paid about 50 to 60 cents per score starting in 2018. In 2023 the royalty was tiered by lender, from about 60 cents up to about $2.75, and in 2024 it was about $3.50. For 2025 FICO set its wholesale royalty at $4.95 per mortgage score, more than eight times the earlier level. These are FICO's own stated royalties in nominal dollars. Prices for other scores, such as card or auto scores, are not public.
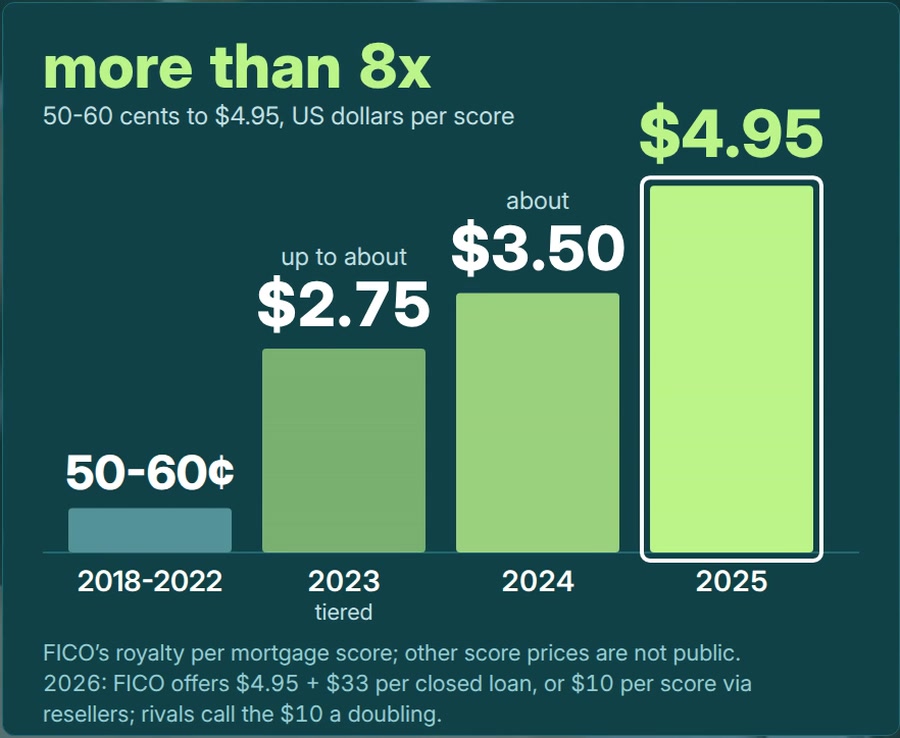
The price for 2026 is described in two ways. In October 2025 FICO offered lenders $4.95 per score plus a $33 fee per borrower on closed loans, or $10 per score through resellers, which FICO calls the average price the credit bureaus previously charged. Equifax, one of those bureaus, said FICO had more than doubled its 2026 pricing, from $4.95 to $10. The two companies describe the same offer differently.
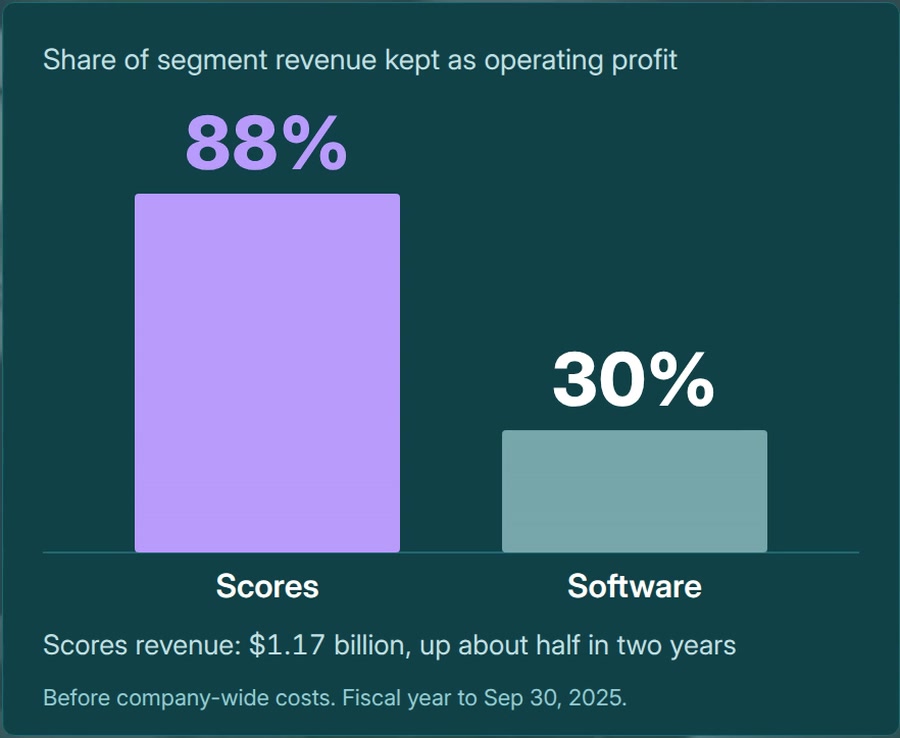
Those fees show up in FICO's accounts. In fiscal 2025, the year to September 30, 2025, the Scores segment brought in $1.17 billion of revenue, up about half from fiscal 2023. FICO's 10-K attributes the growth mainly to a higher unit price, along with more mortgage originations. The segment operating margin was 88%, meaning 88 cents of operating profit per dollar of segment revenue, against 30% in the Software segment. Both are measured before company-wide costs, so neither describes the company as a whole.
A common reading is that a high score means a safe loan, and the 2008 crisis shows the limits of that. A study by Adelino, Schoar and Severino in the Review of Financial Studies (2016) followed purchase mortgages that fell 90 days or more behind within three years. Borrowers with FICO scores above 720, close to the median, accounted for 9% of the delinquent mortgage dollars among 2003 loans and 23% among 2006 loans, as house prices fell, the study finds. These are shares of bad mortgage dollars, not default rates, and they do not show that high-score borrowers defaulted more than low-score ones.
The stock has followed the mortgage rules. In July 2025 the Federal Housing Finance Agency, the housing regulator, let mortgage lenders choose the credit score, which opened the door to the rival VantageScore, and FICO's 10-K lists that change as a risk. On September 29, 2026, the shares closed 26.5% lower in one day, after news reports that both scores would share one pricing grid at Fannie Mae and Freddie Mac, as reported by Yahoo Finance. FICO reports fiscal 2026 results on November 4, 2026, so the company figures here are for fiscal 2025.
The mechanism is a fee on each score a lender pulls. While one model is the default for mortgages, the price per score can rise and most of the extra revenue reaches segment profit, and a rule that lets lenders pick a rival score puts that default position in question.
Watch the short video: YouTube
Sources
- FICO 10-K for fiscal 2025, filed November 7, 2025
- FICO press release, October 1, 2025
- FICO blog, FICO's Adoption and Pricing in the Mortgage Origination Market, March 15, 2024
- FICO blog, FICO's Royalty Pricing, Role and Adoption in the Mortgage Industry, November 6, 2024
- Equifax statement, October 2, 2025
- Adelino, Schoar and Severino, Loan Originations and Defaults in the Mortgage Crisis
- Yahoo Finance, September 29, 2026
- Nasdaq.com FICO historical prices